VinFast Dominates Vietnam's Car Market. So Why Is It Losing Billions?
VinFast leads Vietnam's car market, yet lost nearly $4 billion in 2025. Its rapid growth raises a harder question: can it ever turn a profit?
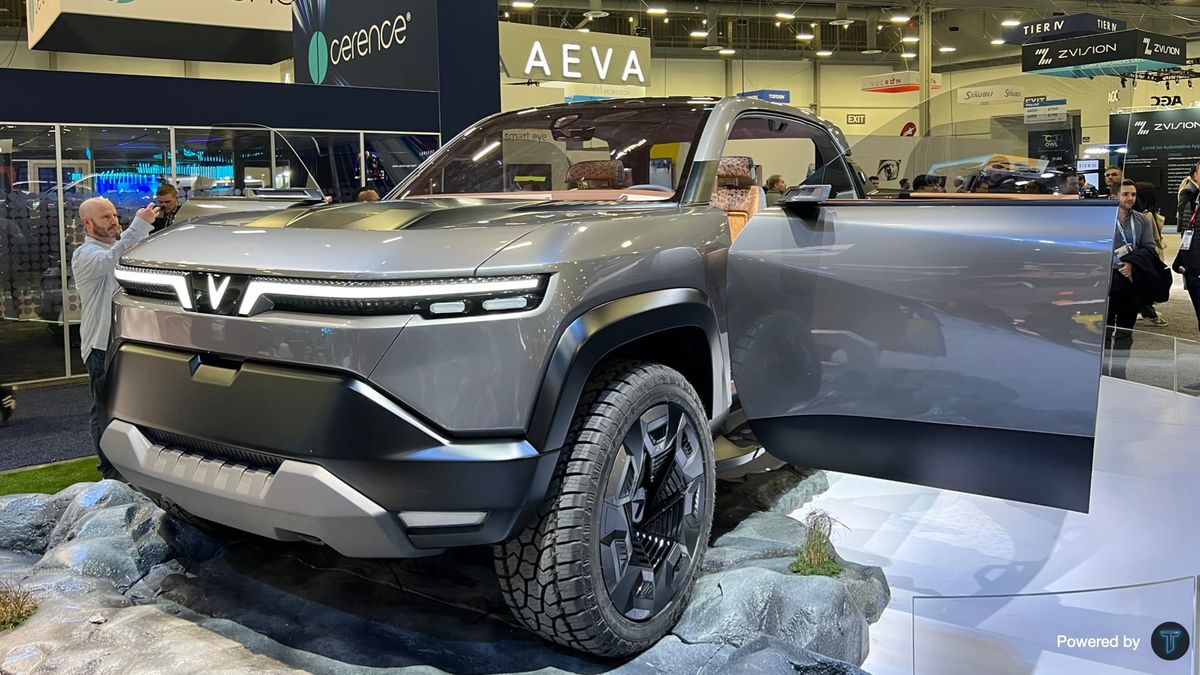
Vietnam's homegrown automaker doubled its electric vehicle deliveries in 2025. Its financial losses grew even larger.
VinFast achieved something remarkable in 2025. The Vietnamese electric vehicle manufacturer delivered more cars in its home market than any other automotive brand, surpassing established competitors such as Toyota and Hyundai.
Its global vehicle deliveries doubled from the previous year, reaching nearly 197,000. About 175,000 of those vehicles were delivered in Vietnam, where VinFast estimated that it had captured 36% of the passenger car market.
For a company that began producing automobiles only a few years earlier, this was an extraordinary commercial achievement.
The financial results told a less encouraging story.
VinFast reported approximately $3.59 billion in revenue for 2025. Its net loss reached $3.96 billion, up from the previous year. The company was losing more money than it generated in annual revenue.
How could a manufacturer become the dominant automotive brand in its own country while remaining so deeply unprofitable?
Part of the answer lies in how VinFast conquered the Vietnamese market.
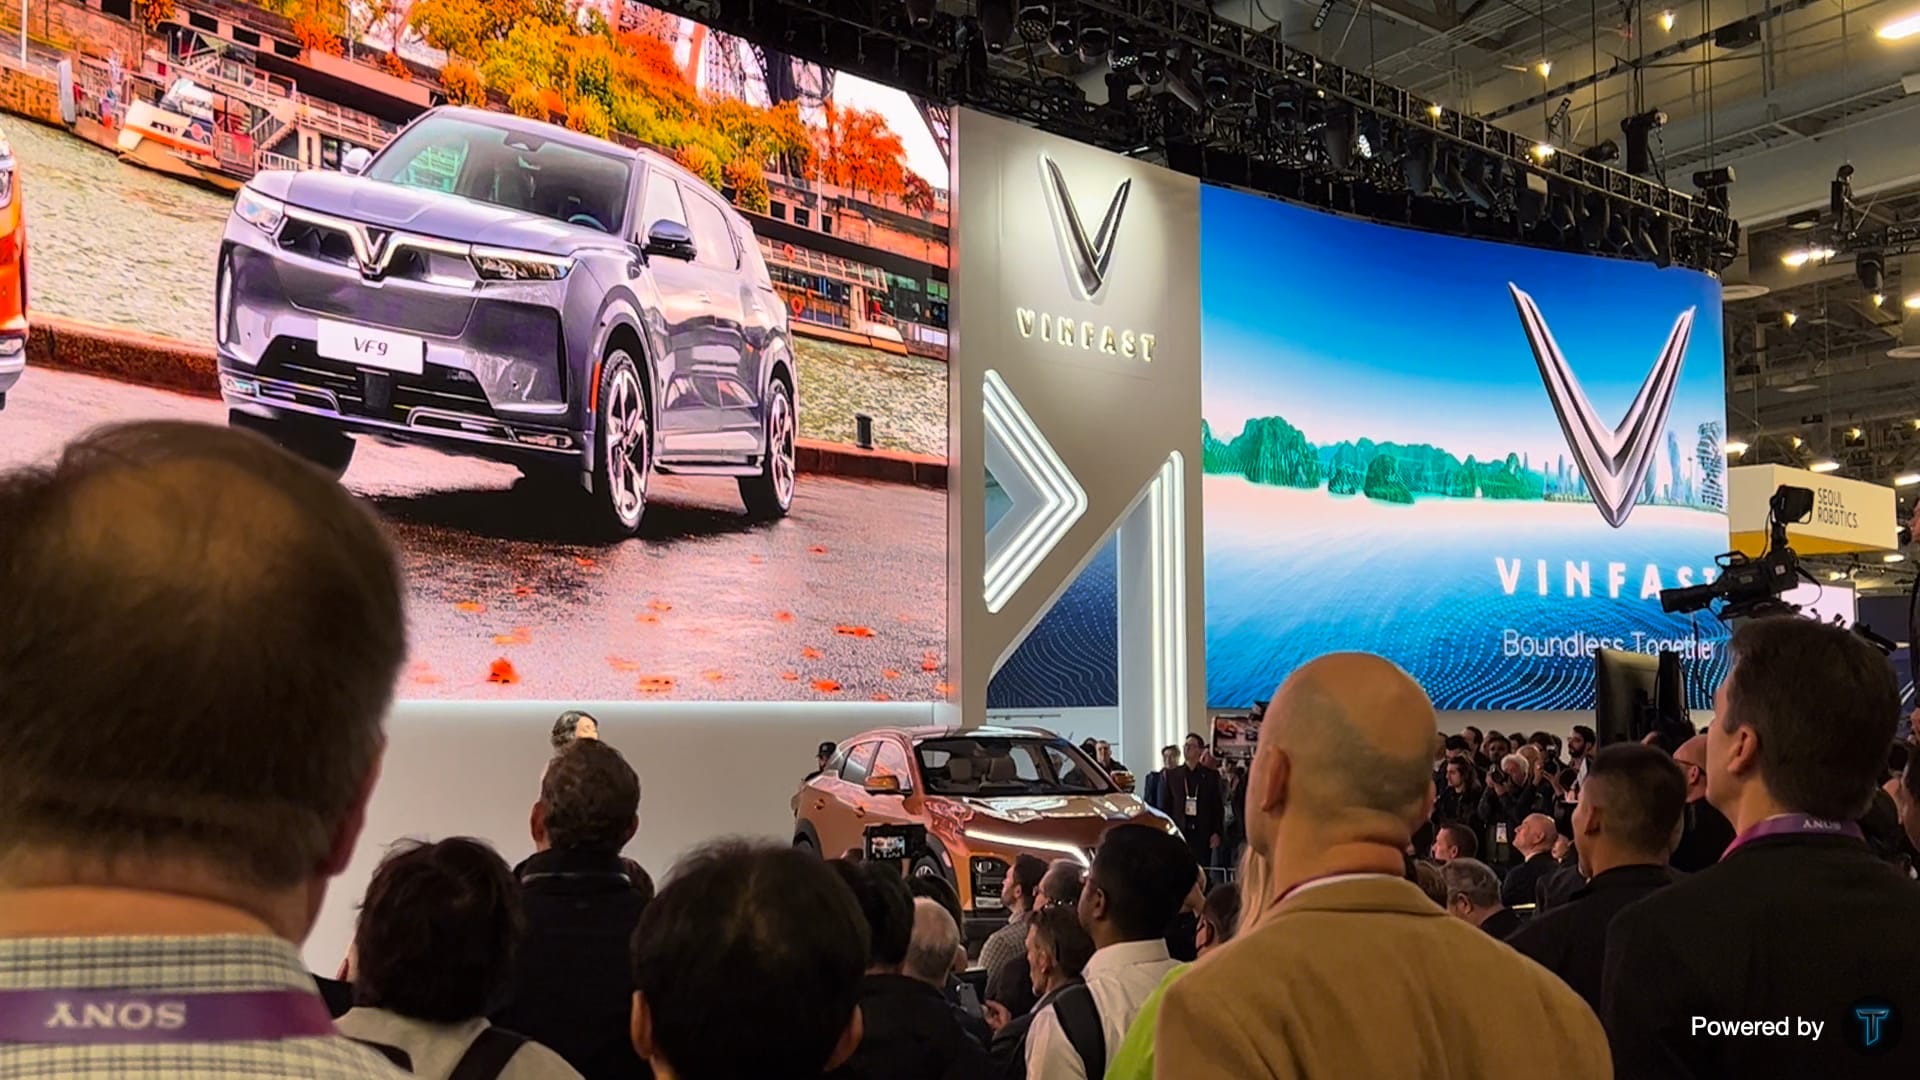
An Electric Car for a Motorcycle Nation
Vietnam has long been a country of motorcycles. In cities such as Hanoi and Ho Chi Minh City, two-wheelers remain an essential part of everyday transportation.
For many households, buying a conventional automobile represents a substantial financial commitment. Vehicle prices, registration expenses, fuel and maintenance costs all influence that decision.
VinFast approached this market with a range of relatively affordable electric vehicles.
Its smallest models were designed for consumers who might otherwise have considered a motorcycle or an inexpensive gasoline-powered car. The compact VF 3, which began deliveries in 2024, became one of the company's most successful products.
In 2025, VinFast delivered nearly 47,000 VF 3 vehicles globally, alongside more than 44,000 units of the slightly larger VF 5.
These were not expensive electric SUVs competing directly with premium European brands. They were practical vehicles aimed at customers for whom price and everyday operating costs mattered enormously.
The strategy helped VinFast reach a much broader audience.
But affordable vehicles alone do not explain its domestic dominance.
The Advantage of Owning the Charging Network
Electric vehicles face a familiar obstacle in emerging markets: consumers hesitate to buy them without reliable charging infrastructure, while investors hesitate to build charging stations until enough vehicles are on the road.
VinFast had an advantage that many competitors lacked.
V-Green, a charging infrastructure company established by VinFast founder Pham Nhat Vuong, developed a network supporting VinFast vehicles across Vietnam.
The availability of charging infrastructure reduced one of the uncertainties associated with electric vehicle ownership.
VinFast also used aggressive incentives to make the proposition more attractive. Under a program announced in February 2026, individual customers purchasing electric cars could receive up to ten free charging sessions per month at V-Green stations through February 2029, subject to the program's conditions.
For drivers comparing an electric vehicle with a gasoline-powered alternative, several years of free charging can make a substantial difference to the total cost of ownership.
The strategy has a commercial logic. A company trying to establish a new automotive brand can use incentives to attract customers, build familiarity and increase production volumes.
There is, however, a cost.
Charging infrastructure requires investment. Electricity and maintenance are not free, even when customers do not pay for individual charging sessions.
VinFast and its affiliated businesses have been willing to absorb substantial expenses to accelerate electric vehicle adoption.
That approach helped create a market. It did not necessarily create a profitable one.
The Customer Behind the Sales Figures
Another part of VinFast's growth came from an unusual source.
Green and Smart Mobility, better known as GSM, operates electric taxi and mobility services using VinFast vehicles. The company was founded by Pham Nhat Vuong, who also controls VinFast through his business interests.
GSM provided an important source of demand during VinFast's early development.
This arrangement helped the manufacturer place more vehicles into service, increase factory output and establish a visible presence on Vietnamese roads.
It also complicates the interpretation of sales figures.
A vehicle purchased by a fleet operator connected to the manufacturer's founder is a legitimate commercial transaction. But it is different from a vehicle independently chosen by a household comparing several competing brands.
The distinction matters when assessing the strength of consumer demand.
In 2023, VinFast relied heavily on sales to affiliated businesses. By 2025, that dependence had declined considerably. According to the company's preliminary full-year disclosure, approximately 27% of electric vehicle deliveries went to related parties, compared with about 28% in 2024.
The figures suggest that VinFast was becoming less dependent on affiliated buyers, although those transactions still represented a substantial part of its business.
This is meaningful progress. A manufacturer cannot build a sustainable mass-market business indefinitely on purchases from companies connected to its controlling shareholder.
Yet the transition toward broader customer demand has not solved VinFast's financial problems.
The Economics Behind the Losses
Automobile manufacturing is a capital-intensive business.
Factories require expensive machinery and production lines. Engineers must develop vehicles years before they generate revenue. Suppliers need to be paid, inventories managed and warranty obligations supported.
Manufacturers generally expect higher production volumes to spread fixed costs across more vehicles.
VinFast has been moving in that direction.
Its gross margin improved from negative 57.4% in 2024 to negative 45.4% in 2025, according to its audited annual report.
That improvement deserves recognition. It suggests that increased production and changes to the company's cost structure were beginning to have an effect.
But a negative gross margin of 45.4% remains an enormous problem.
In broad terms, VinFast spent approximately $1.45 in direct costs of sales for every dollar of revenue it generated. These costs include more than the physical materials assembled into each vehicle, so the figure should not be interpreted as the exact loss on an individual car.
Even before accounting for the full cost of research, administration and financing, the business was operating at a substantial gross loss.
The scale of the problem becomes clearer further down the income statement.
VinFast spent approximately $395 million on research and development in 2025. Finance costs amounted to about $888 million.
The company also recorded an impairment charge of roughly $238 million related to its planned North Carolina factory, reflecting revised assumptions about the project's timing and development.
These expenses help explain why higher sales did not translate into lower overall losses.
VinFast was expanding production and investing in future vehicles while still struggling to recover the costs associated with its existing business.
The company had improved its manufacturing economics, but not enough to offset the financial burden of its expansion.
Who Is Paying for VinFast's Ambitions?
Most young automakers would struggle to survive losses of this magnitude.
VinFast has an unusually powerful financial backer.
Its parent company, Vingroup, is one of Vietnam's largest business conglomerates, with interests spanning real estate, technology and other industries.
Pham Nhat Vuong, Vingroup's founder, has repeatedly committed substantial personal resources to the automotive business.
VinFast's annual report states that approximately $17 billion had been deployed to fund its operations and capital expenditure since 2017, drawing on Vingroup, affiliated entities and external lenders.
That figure represents cumulative funding from multiple sources, rather than a single investment made by its founder.
The distinction matters because VinFast's survival has depended on several forms of financial support, including loans, equity financing and grants.
This backing has given the company time to develop vehicles, build factories and expand its distribution network while absorbing losses that might have forced a less well-funded competitor to abandon the market.
But financial support does not eliminate the underlying economic problem. It allows the company to continue operating while attempting to solve it.
There is also a broader question for Vingroup.
Capital directed toward VinFast cannot simultaneously be invested elsewhere. The conglomerate must weigh the potential long-term value of building a globally competitive automobile manufacturer against the continuing financial demands of the business.
Pham Nhat Vuong has demonstrated an extraordinary willingness to support VinFast. Whether that commitment eventually produces a self-sustaining manufacturer remains uncertain.
Can VinFast Grow Its Way to Profitability?
VinFast's domestic success should not be dismissed.
The company has established an automobile manufacturing business in a country without a long history of producing globally recognized passenger cars. It has developed a broad electric vehicle lineup and built a substantial customer base.
Its 2025 results also show that greater production volumes can improve gross margins.
But the remaining distance to profitability is considerable.
VinFast needs to lower manufacturing costs, improve factory utilization and generate enough revenue from vehicle sales to cover the continuing expenses of operating and expanding the business.
It must also demonstrate that customers will keep buying its vehicles when promotional incentives become less generous.
That is a difficult task in Vietnam, and potentially harder overseas, where established manufacturers offer competing products backed by mature service networks and stronger brand recognition.
The company's expansion into international markets may eventually provide the additional sales volume needed to improve its economics. It could also create new financial pressures if demand fails to justify the investment.
For now, VinFast presents an unusual case in the global automobile industry: a company that has achieved domestic market leadership before demonstrating that it can manufacture and sell cars profitably.
Its rise has been rapid. The losses have been substantial.
The next stage of VinFast's development will be measured less by how many vehicles it can deliver than by how much it costs to deliver them.
At some point, the company must prove that it can finance its own growth.
Until then, Vietnam's automotive success story will remain an expensive one.
For research inquiries or collaboration, contact: ceo@technorns.com